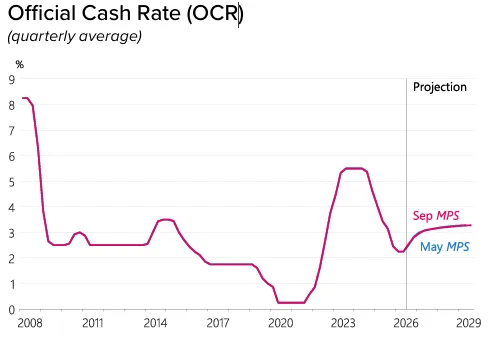
In October, the Reserve Bank of New Zealand's (RBNZ) Monetary Policy Committee surprised most economic commentators by keeping the Official Cash Rate (OCR) steady at 2.75%.
However, it added that if inflation persisted that it would need to increase the OCR at future meetings: "Tighter monetary policy is likely to be required but remains conditional on the economic outlook."
And, it seems, inflation is persisting. Stats NZ's most recent Selected Price Indexes, which comprise around half of the Consumers Price Index's inflation data, show prices continuing to rise, driven by higher fuel costs.
So, it's pretty much a given that the RBNZ will lift the OCR at its next meeting in December – something that the RBNZ has been signalling clearly.
Its most recent OCR tracker continues to show the OCR lifting to 3.2% by the end of 2027.
And in its Financial Stability Report (November 2026), it says: "We expect the average mortgage rate paid by borrowers to increase from around 4.8% to 5.4% over the next year, based on current mortgage rates and market pricing for future interest rates."
So given that the RBNZ is flagging higher OCR and mortgage rates, what are the major banks predicting over the coming months? Let's take a look.
Bank OCR predictions
Below are synopses of the banks' outlooks. See below for a more detailed overview of each bank's prediction and, historically, where mortgage rates have sat in relation to the OCR.
- ANZ: The ANZ is predicting that the OCR will rise to 3% by the end of this year, before hitting 3.5% by March, where it will remain until at least mid-2028. Mortgage rates will increase over next year, but there won't be much difference between shorter- and longer-term fixed rates.
- ASB: Expects the RBNZ will lift the OCR to 3.5% by March 2027. The bank says there's lots influencing the mortgage rate market but, ultimately, rates are "expected to go up, not down". And, if inflation isn't reined in, they could increase faster than expected.
- BNZ: Expects the OCR will hit 3% by the end of this year, and lift to 3.75% by March 2027. As a result, the bank expects all mortgage rates to track slightly higher over the summer.
- Kiwibank: Thinks the OCR will peak at 3.25% by mid next year, but that the market has been too bullish pricing in the OCR lifting further, to 4%. So, as a result, predictions will have to be reassessed, which will lower the pressure on mortgage rates over the coming year.
- Westpac: Expects the OCR to keep rising, and to hit a high of 4% by the end of next year. These increases will put pressure on mortgage rates, so fixing now for a term between two and five years makes good sense, as it insulates borrowers from mortgage rate hikes.
ANZ
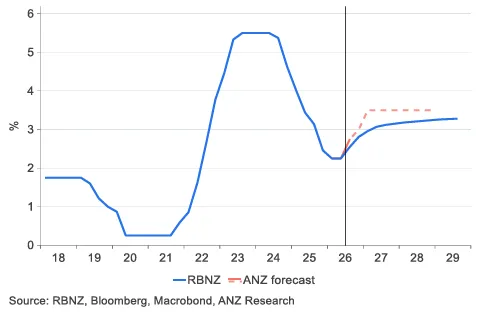
The ANZ is predicting that the OCR will rise to 3% by the end of this year, before hitting 3.5% by March, where it will remain until at least mid-2028.
On the back of its prediction, it sees mortgage rates following suit, lifting over the next four months, before remaining steady:
Rate | Dec 2026 | March 2027 | June 2027 | Sept 2027 | Dec 2027 | March 2028 | June 2028 |
|---|---|---|---|---|---|---|---|
Floating | 6.7% | 7.3% | 7.3% | 7.3% | 7.3% | 7.3% | 7.3% |
1-Year | 5.3% | 5.5% | 5.5% | 5.5% | 5.5% | 5.5% | 5.5% |
2-Years | 5.4% | 5.5% | 5.5% | 5.5% | 5.5% | 5.5% | 5.5% |
3-Years | 5.6% | 5.8% | 5.8% | 5.8% | 5.8% | 5.8% | 5.8% |
5-Years | 5.9% | 6.0% | 6.0% | 6.0% | 5.9% | 5.9% | 5.9% |
And when it comes to fixing, ANZ says that two- and three-year fixed rates are the current sweet spot, because they offer a good balance of cost and certainty – as they're not much more expensive than fixing for one year – and protect home owners against possible further mortgage rate rises if higher oil prices require the OCR to go higher than the bank or markets expect.
ANZ OCR Forecast
ASB
Like their counterparts at the ANZ, ASB's economists expect the RBNZ will lift the OCR to 3.5% (their estimate of a neutral) by March next year. From there, they forecast it to remain at that level for the next two years.
In its recent Home Loan Rate Report, ASB makes two clear points:
- Mortgage interest rates are expected to go up
- There's more at play than the OCR
The bank says there's lots influencing the mortgage rate market but, ultimately, rates are "expected to go up, not down". And, if inflation isn't reined in, they could increase faster than expected.
For borrowers it's no longer about waiting for the lowest rates, because that point is behind us. Now it's about balancing personal needs and flexibility with a view to minimising the cost of borrowing over the long term.
BNZ
BNZ's chief economist, Mike Jones, wrote that he expects the OCR will hit 3% by the end of this year, and lift to 3.75% by March 2027.
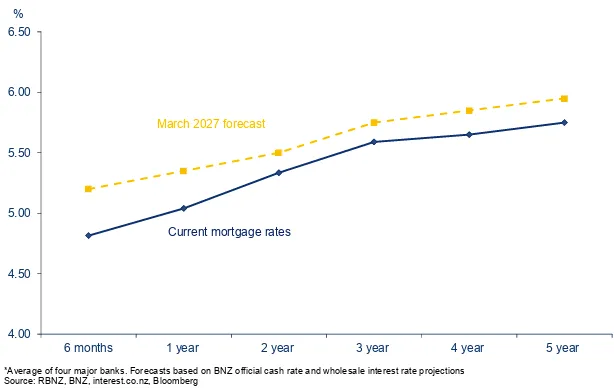
As a result, he expects all mortgage rates to track 20-50bp higher over the next four months, as you can see from this graph:
BNZ Mortgage Rates Forecast
He noted that over the past year, borrowers realised that mortgage rates had bottomed out, and were fixing for longer. As a result, two-year fixed terms have become popular once again.
Kiwibank
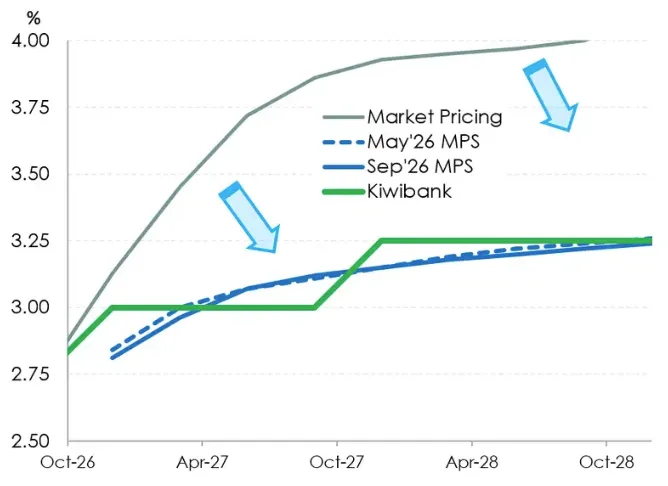
The economists at Kiwibank are always dovish when it comes to the strength of the NZ economy and the need for OCR hikes. But they do still expect that the RBNZ will lift the OCR to 3% by early next year, and then on to 3.25% by mid-2027.
However, Kiwibank adds that the market has been too eager to price in the OCR lifting further, to 4%, and thinks that, as a result, predictions will have to be reassessed, which will "lower the pressure on all retail rates, particularly mortgage rates".
Kiwibank OCR Forecast
Westpac
Like everybody else, Westpac was surprised that the RBNZ didn’t lift the OCR back in October.
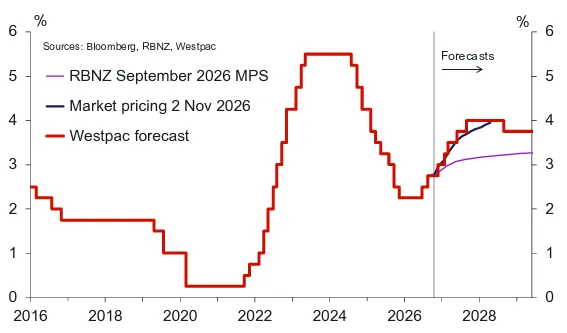
However, like everybody else, it now thinks rate rises are imminent: it expects a 25bp hike in December, and then further 25bp hikes in February and March, increasing the OCR to 3.5% by autumn.
And, as you can see from the below graph, by the end of next year, Westpac expects the OCR to reach a peak of 4%:
Westpac OCR Forecast
As a result, the bank thinks that mortgage rates are sure to follow. So fixing for a longer term, between two and five years, is an attractive option, as it will "insulate borrowers from a trend higher in the OCR over the next couple of years".
Mortgage rates vs OCR
Looking at current predictions, over the next couple of months the OCR should rise to around 3%. So, on such a forecast, where can we expect interest rates to settle?
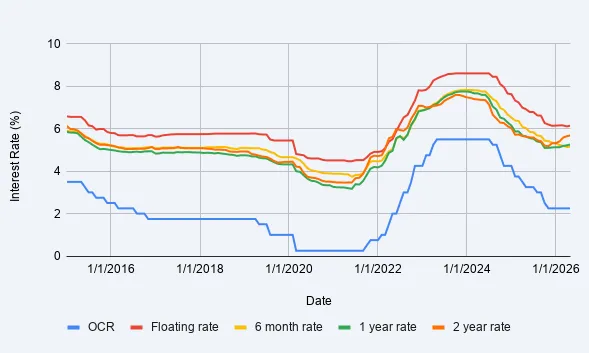
The last time the OCR sat around 3% was 10 years ago, and then the banks' carded shorter-term rates were just over 5%, which is exactly where they're sitting now. And as you can see below, even though the OCR did subsequently drop to below 2% in the years leading up to the pandemic, mortgage rates remained pretty static.
Although it's worth pointing out that a bank's advertised carded rate is different from its special rate. This means, if you've a 20%-plus deposit and a good credit history, you're very likely to qualify for a better deal.
OCR vs Mortgage Rates 2015-2026