canstar
canstar

Compare from a range of home loan providers

provider logo
provider logo
provider logo
provider logo
provider logo
provider logo
provider logo
provider logo

We do not compare all brands in the market, or all products from our participating brands. At times certain brands or products may not be available or offered to you. Learn more.

Why compare home loans with Canstar?

dollar-sign_icon 60x60

No cost to you

Using our comparison tool to find a better deal is free. We may receive a commission from our Online Partners if you apply for a home loan you find on our site.

lightbulb_icon 60x60

Expert research

Our team of home loan research experts crunch the numbers to rate home loans based on value (price as well as features) to help you compare. Read the home loans methodology.

shopping-basket_icon 60x60

A wide range of lenders

We rate and review over 50 home loans from 8 lenders, which means you can compare and choose products from large and challenger brands, established and new.

clock_icon 60x60

Easy to compare & apply

Our home loan comparison tool allows you to filter your search results so it's easy to find the right product for you. What's more, you can click straight through to many of our Online Partners, making it easy to apply instantly.

How to compare home loans

Architectural engineering concept

Home Loan Award Winners

Our research team has done the hard work, comparing interest rates, costs and features to help Kiwi home owners find home loan products that deliver outstanding value and customer satisfaction.

2026 Outstanding Value Home Loans
award logo
Investment LenderInvestment FixedResidential Fixed
2026 Most Satisfied Customers Award
award logo
Home Loans
2026 Outstanding Value Home Loans
award logo
Investment LenderInvestment Fixed
View award details

Construction Loan tips from our expert

Your rate is important

Rate isn't the only factor to consider when selecting a construction loan, but it's a critical one, especially since most construction loans involve floating rates, which tend to be higher than those associated with fixed-term mortgages.

A low rate means that you'll pay less interest to your bank – especially if you're planning for a lengthy build or experience costly delays.

Don't over invest

Remember that you'll be borrowing against the final value of the property, which includes the land you build upon.

So while you might feel you want to splash out on the best fixtures and fittings for your new home, you need to bear in mind that your home's location will also affect its final market value and not overcapitalise.

Shop around

Always check your rate against what the competition is offering and ask your lender to either match or better the deal by offering either a lower rate, a bigger cashback deal, or both. And if you're not satisfied, shop around!

Guide to home loans

What is a construction loan?

A construction loan is a loan designed for people building a home, instead of buying an established property. It has a different loan structure to a conventional mortgage for a pre-existing home.

Usually, a construction loan is drawn down progressively. This means that you draw down the loan (increase your borrowing) in stages, as you pay for the progress of your new build. For example, as each stage of your home is completed, the builder will invoice you for the work done. You then submit that invoice to your lender for payment.

The amount available to borrow is based partly on the estimated value of the property upon its completion. And a construction loan usual has a variable interest rate, until the last payment on the house is made, when you renegotiate with your lender to switch to a standard mortgage.


How do progress payments work?

Once a construction loan has been approved and the construction of the property is underway, lenders make progress payments throughout the stages of construction. Generally, the payments are made upon completion of five stages:

1. Slab down

When the foundations of the property are laid. This involves the levelling of the ground, as well as the plumbing and waterproofing of the foundation.

2. Frame stage

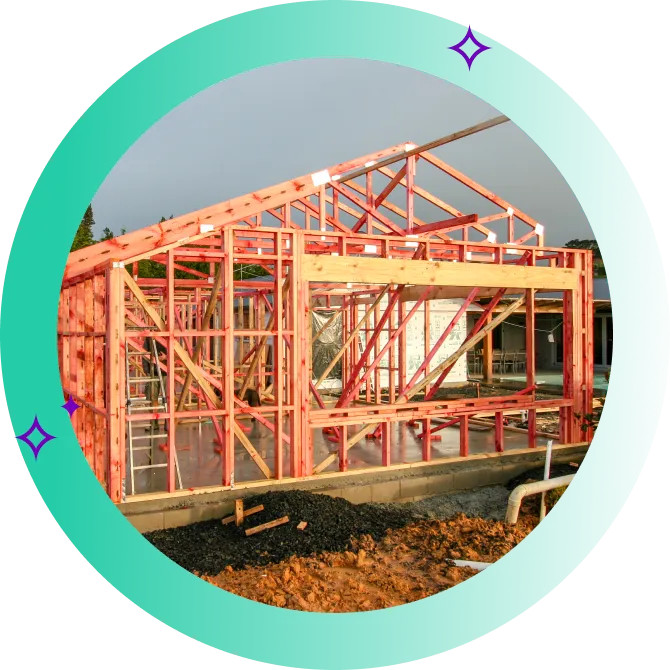
Completion of the frame of the property. It covers partial brickwork, the roofing, trusses and windows.

3. Lock-up

Building of the external walls and the addition of windows and doors. At this stage the house becomes lockable, hence the term lock-up.

4. Fit-out or fixing

Completion of the internal fixtures and fittings. It covers the internal walls and ceilings, part-installation of cupboards and benches, plumbing, electricity and gutters.

5. Completion

The conclusion of contracted items (e.g. builders, equipment), as well as any finishing touches, such as plumbing, electrics and general cleaning-up.

As the loan is progressively drawn down, interest and repayments are calculated based only on the funds used. For example, if by the third progressive payment only $150,000 has been drawn down on a $300,000 loan, interest is only charged on $150,000.

It's also important to note that most banks require you to use all of your equity before they release the next payment.


How to get a construction loan

Getting approval for a construction loan is a different process to applying for a standard home loan on an existing home. To ensure a smooth process, the first step is to present your lender with professional plans for your property.

A property appraiser will then review the plans to determine the expected value of the completed property. This is because, when considering your mortgage, the lender will review not only your construction bill, but the value of the finished home.

Once the plans have been reviewed, your lender will ask you to approve a loan offer for the property. At this point you pay your deposit, as you would with most other types of home loan. This acts as security for your lender. And, as with a normal home loan, the more you can save for your deposit the better.

At each stage of the construction process, you'll need to confirm that the work has been done. To do this, you complete and sign a drawdown request form, and send it to the construction department of your lender.


Can you use a standard home loan instead of a construction loan?

Yes. If you've enough equity in the land you're building on, or in another asset, such as an investment property or family home, you'll be able to borrow the amount that you need, without using your to-be-constructed house as security.

The advantage of redrawing from an existing loan is that you will have access to the entire lump sum of money. This means you'll be able to pay all construction costs as they come in, including smaller incidental costs, instead of having to access progress payments through your bank. This is a particular advantage for owner-builders and those who are DIYing some parts of the construction.

A potential disadvantage is that from the moment you fully drawn down your loan, you'll pay interest on the full amount. But this can be mitigated by placing any not-yet-spent construction money in a 100% offset account against your loan.


What are owner-builder mortgages

An owner-builder mortgage is a construction loan for people who intend to build their house themselves, without the help of a professional builder.

Lenders can be hesitant to accept applications for owner-builder loans, and approval conditions are stricter, because of the higher risks involved.

For if you are an unprofessional owner-builder and botch the build, your mortgage provider has a greater chance of not recouping its money.


What costs are associated with a construction loan?

Compared to purchasing an existing dwelling, building a new home comes with addition costs, these include:

  • Architect or draftsman.
  • Construction professionals, including: builders, engineers, tradies, quantity surveyors and project managers.
  • Contract works insurance.
  • Council documents, including LIM report.
  • Project delays and cost blow-outs.
  • Resource and building consent.
  • Solicitor fees.
  • Temporary housing costs and storage fees.
  • Valuations.
  • Water, power and broadband connection costs.

How to reduce the cost of building a new home

There are things you can do to keep building costs down:

  • Avoid elevated sites, exposed to the wind, and unsuitable ground that requires engineering design, or places with difficult site access
  • Build a smaller home
  • Buy land in cheaper new greenfield developments, outside of more expensive inner-city suburbs
  • Don't build cantilevered decks, roofs and floors
  • Don't use expensive cladding, like cedar, or roofing, such as tray roofing
  • Don't use large square metres of glass (requiring steel portals)
  • Have smaller rooms, not open, expansive living areas that requiring engineering due to the lack of walls to brace
  • If possible buy a flat level site, avoid steep (or even not so steep) sites that require retaining walls
  • Say no to any build methods that are time consuming
FAQs about construction loans

Generally speaking, the process of getting a home loan involves comparing your options, working out how much you can afford to borrow for the property you want to build, and then applying for a specific home loan – either directly to the lender of your choice or indirectly via a mortgage broker.

If the lender approves your application and agrees to lend you the money you requested, it will offer this money to you in the form of a home loan. You'll then need to pay back the loan over time, in line with the lender's terms and conditions.

The best construction loan rate is subjective, and depends on your needs and circumstances.

During the construction period, when the loan is on a variable rate, your focus may be one with the lowest interest rate.

However, once you complete your build, and you can move your loan to a regular fixed-rate mortgage, then the best loan may be one that allows you to make additional repayments, or one with an offset account, that you can use for everyday banking while lowering the balance of your home loan.

Comparing home loans or speaking to a qualified mortgage broker can be ways to help find the best home loan rate for your financial situation.

If you're looking for the best construction loan for your property-ownership needs, then some important things to consider are:

  • The mortgage rates on offer from a lender. Are they competitive?
  • How much deposit do you have?
  • After the build is finished, do you want an offset mortgage or line of credit facility?
  • What fees and charges are attached to the home loan product?

First home buyer loans

Regular home loans

The following home loan providers are listed on Canstar’s home loan comparison tables:

  • ANZ
  • ASB
  • BNZ
  • Heartland Bank
  • Kiwibank
  • SBS Bank
  • The Cooperative Bank
  • TSB Bank
  • Westpac

Please note that these are general explanations of terms used in relation to home loans/mortgages. Policy wording may use different terms, and you should read the terms and conditions of the relevant policy to understand the inclusions and exclusions of that policy.

Additional repayments – additional repayments can be made on a regular basis above the minimum required repayment. Additional fees and charges may apply.

Annual percentage rate – total charge for the loan including fees and interest expressed as a percentage, which allows you to compare across the market.

Application fee – fee paid to the lender for setting up a home loan.

Appraisal fee – fee charged for a professional opinion about how much a property is worth.

Arrangement fee – fee some lenders charge for arranging your loan.

Asset – a resource you own and from which you expect to earn future economic benefits.

Automatic transfer – a system that is set up to automatically transfer money from one bank account into another.

Balloon loan (balloon mortgage) – a loan that has regular payments that do not cover the full loan by the end of the term, meaning a larger lump sum is due at maturity.

Bankruptcy – when someone's debt problems get so serious, they are unable to pay their debts and bills. When this happens, it's possible to apply to a court to be made bankrupt – which means that any assets you have, such as savings, will be used to pay off your debts. Normally, after one year, a person will be discharged from bankruptcy. However, it will still have a negative impact on their credit rating and may stop them getting credit in the future.

Basis points – a basis point is equal to 0.01% interest. For example: 50 basis points is an interest rate of 0.50%.

Bill of sale – a written agreement whereby ownership is transferred, but the original owner is allowed to retain possession.

Biweekly mortgage – a home loan in which the payments are scheduled for every other week, rather than each month.

Break costs – the penalty fees charged when a borrower ends a fixed-rate loan contract before the fixed-rate period expires.

Bridging finance – a short-term loan used when buying a new home before selling an existing home.

Buydown – when a home buyer buys down the interest rate by paying an initial fee upfront, thereby reducing the size of future payments.

Caveat emptor – Latin for let the buyer beware.

Construction loans – a home loan for the purpose of building a new home.

Countersigned – additional signature or signatures to guarantee the validity of a document.

Credit rating – an assessment of the credit-worthiness of an individual or corporation, based on their borrowing and repayment histories.

Credit report – a report from an authorised agency that shows the potential borrower's credit history. Lenders access the information in your file to help them decide whether to lend to you. They can also record a default on your file if you make loan repayments late, or don't pay a utility bill. Every time you make an application for finance, an entry is recorded on your file, showing the lender you applied to, the type of finance, the amount and the date.

Credit/facility limit – the maximum loan amount that a borrower can borrow under their home loan contract.

Current rate – the rate advertised by institutions not including fees, discounts and special offers.

Debt consolidation (consolidation loan) – a loan that replaces multiple loans with a single one, often with a lower monthly payment but a longer period of repayment.

Default – when a consumer fails to fulfil obligations to make the necessary payments on a loan.

Deposit guarantee – a substitute for a cash deposit to assist with the purchase of a property. Useful when the buyer has cash tied up in term deposits or shares, but the buyer is still required to pay the full purchase price at settlement.

Disbursements – the various costs your solicitor or conveyancer must pay to other organisations and bodies on your behalf. Your solicitor or conveyancer will itemise the disbursements on the invoice they send you.

Down payment – the initial payment of the home loan, usually a small proportion of the total price.

Drawdown rate – the date on which the borrower first uses the loaned money.

Empty nester – someone whose children have moved out of their house. They are typically in the market for a smaller home.

Encumbrance – an outstanding liability or charge on a property.

Equity – the residual claim to ownership which the purchaser holds. For example, if a house is valued at $1,000,000 and the owner has a loan of $600,000 against the property, the equity in the property is $400,000.

Extra repayments – some home loans allow you to make extra payments earlier/greater than the required amount.

Family guarantee – a family member who acts as a financial guarantor to secure a home loan.

Fixed rate home loan – a loan with a fixed rate of interest, usually set for between one to five years.

Floating rate home loan – a loan on which the interest rate can go up and down, generally in line with changes to the Official Cash Rate.

Foreclosure – when a homeowner defaults on their mortgage and has their interest in the property cut off. Usually leads to a forced sale of the home, with the proceeds going towards the mortgage debt.

Guarantee – any undertaking that promises to pay an amount of funds upon the presentation of a claim or some other defined event (usually a financial default on the part of the entity for which the guarantee was issued).

Guarantor – a person or company that endorses an agreement to guarantee that promises made by the first party (the borrower) to the second party (lender) will be fulfilled and assumes liability if the borrower fails to fulfil them (defaults). In case of a default, the guarantor must compensate the lender and usually acquires an immediate right of action against the borrower for payments made under the guarantee.

Interest only home loan – payments pay the interest charged for a period of time. At the completion of the interest only period payments will revert to principal and interest repayments.

Loan amount – the amount of money to be borrowed. The products shown will be limited to those available for the loan amount entered.

Loan purpose – the primary reason or purpose for borrowing the money.

LVR – the maximum loan to value ratio (LVR) available on a loan. The LVR is the percentage of the property value which is being borrowed. For example, a property valued at $1,000,000 with an $800,000 loan would have a LVR of 80%. A deposit of $200,000 would then be required. The products shown will be limited to those available for the LVR selected.

Monthly repayment – the estimated minimum monthly repayment. For principal and interest loans this is based on the interest rate, selected loan amount and loan duration. For interest only loans this is based on the interest rate and selected loan amount considering the repayment of interest accrued over a one-month period.

Not rated – applied when a product is not eligible for a Canstar Star Rating.

Offset account – money placed into an offset account reduces the amount of interest charged on your home loan. Additional fees and charges may apply.

Principal and interest – principal and interest repayments pay down a portion of the loan balance as well as the interest accrued.

Providers – home loan providers on the Canstar database.

Redraw facility – a redraw facility allows restricted access to repayments that have been made over and above the minimum required repayment. Restrictions may include a waiting period to access the funds, limited number of redraws, fees, etc. Additional fees and charges may apply.

Repayment type – the repayment type is the way in which the loan is either repaid or paid for including principal and interest or interest only.

Star Rating – Canstar's Star Ratings are unique, value-based ratings from five to one, with 5-Star Ratings representing the best performing products in Canstar's assessment. See About Star Ratings for more details.

Variable interest rate – a variable interest rate loan has an interest rate that is subject to change.

As Canstar's Group Manager, Research & Ratings, Josh Sale is responsible for the methodology behind Canstar's diverse suite of Star Ratings and Awards and leads the teams that deliver them. With a background in economics and finance and a Master's in data science, Josh has spent the past ten years building ratings that help connect consumers with the right product for them.
Josh is passionate about helping consumers get hands-on with their finances. Josh has been interviewed by media outlets such as the Australian Financial Review, news.com.au and Money Magazine.
You can follow Josh on LinkedIn, and Canstar on X and Facebook.


Bruce Pitchers is Canstar's NZ Editor. An experienced finance reporter, he has three decades’ experience as a journalist and has worked for major media companies in Australia, the UK and NZ, including ACP, Are Media, Bauer Media Group, Fairfax, Pacific Magazines, News Corp and TVNZ. As a freelancer, he has worked for The Australian Financial Review, the NZ Financial Markets Authority and major banks and investment companies on both sides of the Tasman.
In his role at Canstar, he has been a regular commentator in the NZ media, including on the Driven, Stuff and One Roof websites, the NZ Herald, Radio NZ, and Newstalk ZB.
Away from Canstar, Bruce creates puzzles for magazines including Woman’s Day and New Idea. He is also the co-author of the murder-mystery puzzle book 5 Minute Murder.


Important Information

For those that love the detail